Medicare Broker Versus Online Comparison: Core Differences
When you're approaching Medicare eligibility, the decision between working with a Medicare broker or using an online comparison tool shapes not just your plan selection, but your entire healthcare experience. A Medicare broker versus online comparison represents two fundamentally different approaches to navigating one of the most complex decisions in retirement.
A Medicare broker is a licensed insurance professional who represents you directly. They work with multiple insurance carriers, meaning they can access and compare plans across different companies. An online comparison tool is a digital platform where you enter your information and the system displays available options based on your inputs. The distinction matters because it affects what plans you see, how recommendations are made, and what support you receive after enrollment.
The core difference isn't just convenience. It's about representation. When you work with an independent broker, someone is actively advocating for your interests. When you use an online tool, you're making decisions based on algorithms and your own research.
Here's what separates these two paths: a broker asks questions about your health, your doctors, your medications, and your financial situation. Then they filter plans through that lens. An online tool asks some of these questions, but the recommendations depend entirely on the tool's algorithm and how comprehensively you filled out your information. Neither approach is inherently wrong, but they serve different needs.
How to Choose a Medicare Broker: What Makes One Right for You
The question isn't whether to work with a broker, it's whether you're working with the right one. Not all brokers operate the same way, and understanding what to look for prevents costly mistakes down the road.
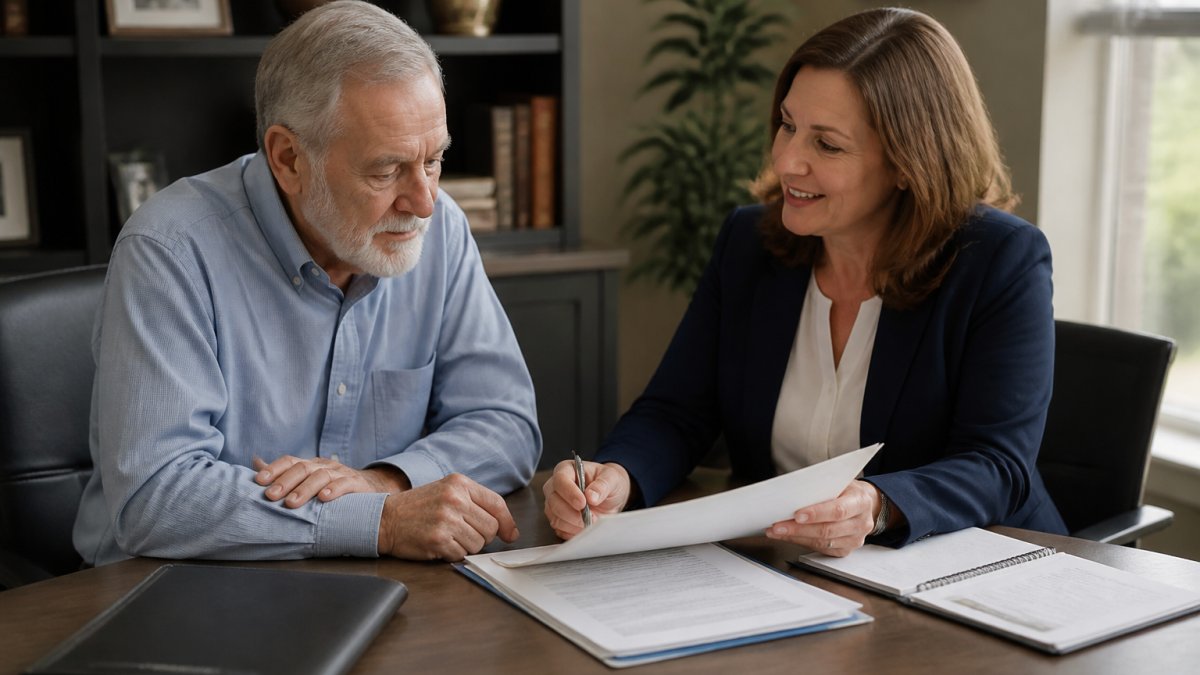
Senior adult meeting with an insurance professional at a desk, reviewing Medicare plan documents together in a warm, professional office setting
An independent broker can access plans from multiple insurance carriers. A captive agent represents a single company and can only show you that company's plans.
Look for a broker who asks detailed questions before making recommendations. A good broker wants to know about your current doctors, your prescriptions, your anticipated healthcare needs, and your budget constraints. They're not just matching you to plans, they're matching you to plans that fit your specific situation.
Verify their credentials. Medicare brokers must be licensed in your state (Registration and Training for Marketplace Agents and Brokers). You can confirm this through your state's insurance department. A broker should also be willing to explain how they're compensated and whether you pay any fees directly.
Ask about ongoing support. The best brokers don't disappear after you enroll. They conduct periodic reviews of your coverage, help you understand your benefits, and assist with claims issues. This lifelong consulting relationship is something an online tool cannot provide.
Plan Access and Representation: Independent Brokers vs. Online Tools
The number of plans you can access depends on which path you choose, and this directly affects your coverage options and costs.
An independent broker can show you Medicare Advantage plans, Medicare Supplement plans, and Part D prescription drug coverage from multiple insurance companies. Because they work with various carriers, they're not limited to any single company's offerings. This breadth matters because plan features, networks, and costs vary significantly between carriers.
Online comparison tools display plans based on their partnerships and database. Some tools have access to many carriers; others have limited partnerships. The tool's algorithm then filters those options based on your inputs.
A Medicare broker's representation means they're accountable to you. If a plan doesn't work out as expected, you have someone to call. They can help you understand why something isn't covered, assist with appeals, and help you switch plans if needed. Online tools provide resources and FAQs, but they don't provide direct advocacy.
The representation difference extends to how recommendations are made. A broker synthesizes information about your health, your network of doctors, your medications, and your financial situation, then recommends specific plans with explanations. An online tool presents options that match your criteria, but the interpretation and decision-making falls entirely on you.
Questions to Ask a Medicare Broker Before You Commit
Before you work with a broker, ask these questions to ensure they're the right fit for your situation.
How many insurance companies do you work with? This tells you whether they're truly independent or limited in their options. More carriers means more plans to compare.
How do you get paid, and will I pay any fees? Most Medicare brokers are compensated by insurance companies through commissions, not by clients. This should be the case.
Can you explain how you'd approach my specific situation? A good broker asks about your health, your doctors, and your medications before recommending plans. They should be able to walk you through how they'd evaluate options for someone like you.
What happens after I enroll? Ask about periodic reviews, ongoing support, and how to reach them if you have questions. The best brokers stay involved throughout your Medicare years, not just during enrollment.
How do you handle conflicts between my interests and higher commissions? This is a direct question, but it matters. A broker should acknowledge that different plans pay different commissions and explain how they ensure recommendations are based on your needs, not commission size.
Can you provide references or examples of how you've helped clients in similar situations? Real examples reveal how a broker thinks through complex decisions.
Medicare Broker Commissions: How They're Paid and What It Means for You
Understanding broker compensation removes a major source of confusion and concern. Many people worry that brokers push them toward plans that pay higher commissions, leaving them in suboptimal coverage.
Here's how it works: Insurance companies pay brokers a commission when they enroll someone in a plan (Agent Broker Compensation). The commission comes from the insurance company, not from you. You don't pay a separate fee to a broker for their time and expertise. This is standard across the industry.
The commission structure varies by plan type and carrier. Medicare Advantage plans typically pay different commissions than Medicare Supplement plans. Part D plans have their own commission structure.
The safeguard is that a broker's long-term success depends on client satisfaction and retention. If a broker recommends a plan that doesn't work for you, you'll likely switch to a different broker next year. Over time, brokers who prioritize commissions over client outcomes lose business.
At SafelyRetire, our approach is straightforward: we recommend the plan that best fits your situation and explain what we're recommending and why. This transparency protects both you and us. If you ever question whether a recommendation was driven by commission or by your needs, you can ask to see our analysis.
The key is knowing that commissions exist, understanding they don't come from you, and working with a broker who's transparent about how they handle the potential conflict.
How to Compare Medicare Plans Online: Verification and Limitations
Online comparison tools serve a real purpose, but they come with blind spots. Knowing how to use them effectively and recognizing their limitations helps you make better decisions.
Start by understanding what the tool is actually comparing. Most online tools compare premiums, deductibles, copays, and out-of-pocket maximums. Some include provider network information. Fewer tools fully capture the nuances of coverage restrictions, prior authorization requirements, or specialty drug tiers.
Verify the tool's plan database. Some tools have partnerships with major carriers; others have limited access. Check whether the tool displays plans from all major carriers in your area or only a subset.
Test the tool's recommendation logic by entering your information carefully. Be specific about your doctors, your prescriptions, and your anticipated healthcare needs. Generic answers produce generic recommendations. The tool can only work with the information you provide.
Cross-reference the tool's recommendations against official Medicare sources. Medicare.gov's plan finder is the authoritative source for plan details. If an online tool shows different information, verify which source is current. Plan details change annually, and tools don't always update simultaneously.
Use online tools as a starting point for research, not a final decision. They're excellent for getting a broad view of what's available and what plans cost.
The limitation most people don't recognize: online tools can't advise you on whether switching plans makes sense.
Making Your Decision: Broker, Online Tool, or Both
The choice between a Medicare broker and an online comparison tool isn't binary. Many people use both, and there's strategic value in that approach.
Use an online tool first to understand what's available in your area and get a rough sense of plan options and costs. This gives you baseline knowledge before talking to a broker.
Then work with a broker to dig deeper into your specific situation. A broker can explain why certain plans are better for your health profile, help you understand the financial implications of different networks, and ensure you're not missing better options.
If you're comfortable with your research and confident in your decision, an online tool may be sufficient. Many people successfully enroll through online platforms every year.
If your situation is complex, multiple health conditions, many prescriptions, concerns about out-of-pocket costs, a broker adds significant value. They're trained to identify coverage gaps and cost inefficiencies that online tools might miss.
Decision Factor
Online Tool
Medicare Broker
Both Together
Research and compare plans
Strong
Strong
Best
Understand your specific costs
Moderate
Strong
Best
Get personalized recommendations
Weak
Strong
Best
Ongoing support and reviews
None
Strong
Strong
Time commitment
Low
Moderate
Moderate
Best for simple situations
Yes
Not necessary
Overkill
Best for complex health needs
No
Yes
Yes
Consider your comfort level with healthcare decisions. If you're confident navigating Medicare's structure and comfortable making decisions based on data, an online tool works well.
At SafelyRetire, we recommend starting with research, whether that's using an online tool or talking to a broker for a free consultation. The goal is making an informed decision, not rushing into coverage that doesn't fit your needs.
Choosing between a Medicare broker and an online comparison tool comes down to what you need most: independent research and self-directed decision-making, or personalized guidance and ongoing advocacy. At SafelyRetire, we help people approaching 65 and current Medicare beneficiaries navigate these decisions by comparing Medicare Advantage, Supplement, Part D, dental, vision, and other coverage options across multiple insurance companies. We believe the best decision is an informed one, made with full understanding of your options and their implications for your health and finances. Book an Appointment with our team to explore which approach makes sense for your situation.
Frequently Asked Questions
What's the real difference between a Medicare broker and an online comparison tool?
A Medicare broker is a licensed insurance professional who works with multiple insurance carriers to recommend plans tailored to your specific health, prescription, and financial situation. Online comparison tools let you enter information and view available plans, but they don't provide personalized guidance or ongoing support. Brokers offer one-on-one consultation, enrollment assistance, and post-enrollment service. Online tools give you independence and speed but require you to evaluate options yourself and make the final decision without expert input.
Do I have to pay fees to work with a Medicare broker?
No. Medicare brokers are typically compensated by insurance carriers, not by beneficiaries. You don't pay a separate fee to use a broker's services. However, verify this with any broker you're considering. Some may offer additional services (like comprehensive retirement planning) that could involve separate fees, but basic Medicare plan comparison and enrollment assistance through an independent broker should be at no cost to you.
Can I compare Medicare plans online without talking to a broker?
Yes. Online comparison tools allow you to enter your information and see available Medicare Advantage, Medicare Supplement, and Part D plans in your area. However, these tools have limitations: they may not show all carriers, may not account for your complete health history or prescription needs, and don't provide personalized recommendations. You'll need to evaluate plans yourself, understand the differences in provider networks and coverage, and make enrollment decisions independently.
How do Medicare broker commissions affect the plans they recommend to me?
Medicare brokers receive commissions from insurance carriers when they enroll you in a plan. Commission amounts vary by plan type and carrier. To protect yourself, ask your broker directly how commissions work, whether they represent all available carriers in your area, and how they ensure recommendations are based on your needs rather than commission size. Independent brokers working with multiple insurers have less financial incentive to push one plan over another compared to captive agents representing one company.
Cooler Weather, More Reasons to Move! Try These Outdoor Activities!
When temperatures begin to drop, spending time outdoors can become more comfortable and enjoyable. Cooler weather offers a great opportunity to step away from screens, get moving and build healthy habits that support your physical and mental well-being. From exploring local trails to enjoying a neighborhood bike ride, simple outdoor activities can help you stay […]