To compare Medicare plans effectively, gather details about your health, medications, doctors, and pharmacies to make the process faster and more accurate.
Here's what to collect:
A list of all your current prescription medications with dosages
Names and contact information for your doctors and specialists
Your preferred pharmacies
Having this ready means you won't waste time searching for details mid-comparison. According to Medicare.gov's plan comparison guidance, entering your prescriptions and providers upfront helps you see accurate costs for each plan option.
At SafelyRetire, we recommend organizing this information in a written or digital file before you start, you'll use it repeatedly as you evaluate plans.
Understanding Your Medicare Plan Options
Medicare is a set of building blocks, and most comparison mistakes happen because people compare blocks that were never meant to be alternatives. Map the four building blocks and how they combine before looking at any specific plan.
The four building blocks
Building block
What it is
Who runs it
Can you add it to Original Medicare?
Can you add it to Medicare Advantage?
Original Medicare (Part A + Part B)
Hospital insurance (Part A) and medical insurance (Part B)
A private plan that delivers your Part A and Part B benefits, usually with drug coverage
Private insurers under contract
No, it replaces Original Medicare
It is the base
Part D
Standalone prescription drug coverage
Private insurers
Yes, required if you want drug coverage with Original Medicare
Usually built into the Advantage plan; standalone Part D is not used
Medigap (Medicare Supplement)
Private policy that pays some of Original Medicare's cost-sharing
Private insurers
Yes, only with Original Medicare
No, illegal to sell alongside Medicare Advantage
The two real paths
Almost every comparison reduces to one of two structures:
Path 1, Original Medicare + Part D + (optional) Medigap
You keep the federal benefit package and can see any provider who accepts Medicare nationwide.
You add a standalone Part D plan for drugs.
You may add a Medigap policy to cap cost-sharing. Medigap letters (A, B, G, N, and so on) are standardized by federal law, so Plan G from one insurer covers the same benefits as Plan G from another, only the premium and the insurer's service differ (Medigap (Medicare Supplement Health Insurance)).
Path 2, Medicare Advantage (usually with built-in Part D)
One private plan replaces Original Medicare and typically bundles drug coverage.
You generally must use the plan's network and follow its rules (referrals, prior authorization for some services).
Every Medicare Advantage plan must set an annual out-of-pocket maximum for in-network care, which gives you a ceiling Original Medicare alone does not.
Where the comparison actually happens
Once you see the two paths, comparison questions become concrete:
Do you want nationwide provider access with no referrals, or are you comfortable inside a network? That single answer usually decides Path 1 versus Path 2.
Do you want a hard annual out-of-pocket ceiling? Path 1 gets one only if you add Medigap; Path 2 has one by law.
How much do you value predictable cost-sharing? Medigap Plan G, for example, pays nearly all of Original Medicare's cost-sharing after the Part B deductible, which makes costs predictable but raises the premium.
Are your drugs covered? On Path 1 you check a standalone Part D formulary; on Path 2 you check the Advantage plan's formulary.
Key Takeaway Do not compare a Medicare Advantage premium against a Medigap premium as if they were the same purchase. They sit on different paths. Compare Path 1 total cost against Path 2 total cost, then compare plans within the path you choose.
A quick decision framework
Choose Path 1 if: you travel widely or split time across states, you want to see specialists without referrals, you are willing to pay a higher premium for predictable costs, and you can qualify for Medigap underwriting (or are in a guaranteed-issue window).
Choose Path 2 if: you want one plan with one card, you are comfortable with a network, you value extra benefits such as dental or vision, and you want a built-in annual out-of-pocket maximum without buying a separate supplement.
Consider Path 1 without Medigap if: you want the widest provider access and are willing to accept uncapped cost-sharing in exchange for lower premiums, but understand that Original Medicare has no out-of-pocket maximum.
Step 1: Gather Your Health and Prescription Information
List every medication you take, including name, strength, and frequency, prescription coverage varies widely between plans.
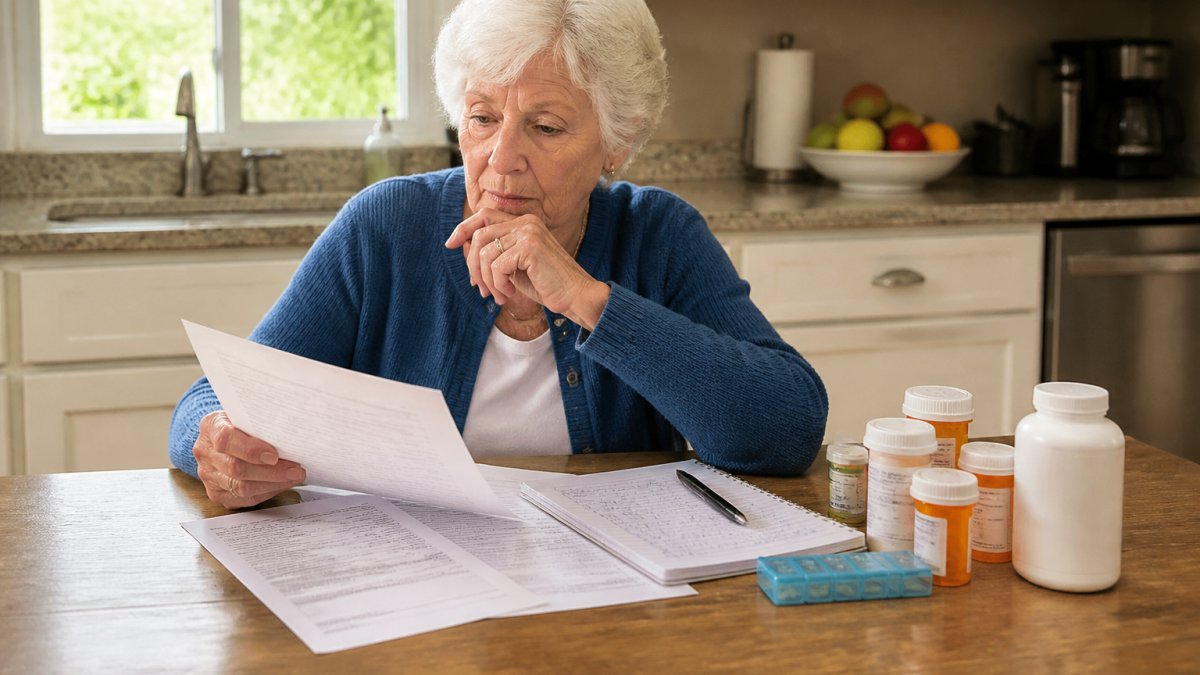
Older adult sitting at a kitchen table with Medicare documents, prescription bottles, and a handwritten notebook, reviewing health information in natural morning light
Write down your doctors' names and specialties, including your primary care doctor, regular specialists, and pharmacy, to check network coverage.
Note any recent diagnoses or ongoing conditions, since plans may have different coverage rules for certain treatments.
Create a simple spreadsheet or document with:
Medication names and dosages
Doctor names and specialties
Current pharmacy name and location
Step 2: Compare Medicare Advantage Plans in Your Area
Use Medicare Plan Finder to search for Medicare Advantage plans available in your ZIP code. Enter your prescriptions and preferred doctors to see accurate costs.
When comparing Medicare Advantage plans, look at:
Monthly premium: What you pay each month
Deductible: What you pay before coverage starts
Copayments: Fixed costs for doctor visits or services
Many Medicare Advantage plans offer extra benefits like dental, vision, or hearing coverage, compare what each includes beyond basic medical coverage.
The lowest premium isn't always the best choice, a higher premium might mean lower copayments or more covered services.
Step 3: Compare Medicare Part D Prescription Drug Plans
If you choose Original Medicare, you must select a Part D prescription drug plan. These plans cover medications not included in Original Medicare.
Part D plans have different cost structures:
Monthly premium: The plan's cost each month
Deductible: Some plans have an annual deductible
Copayments or coinsurance: Your share of medication costs
Check each plan's formulary (list of covered drugs), your medications must be on it to get coverage, and some plans may require different drugs.
Compare estimated annual costs: a low-premium plan might have high copayments, while a higher-premium plan could save money on your drugs.
Step 4: Compare Medicare Supplement Plans for Additional Coverage
If you choose Original Medicare plus Medigap, compare Supplement plans side by side, coverage is standardized across companies.
What differs between Medigap insurers is the premium, shop around for the lowest price on the plan you want.
Medigap plans to consider:
Plan A: Lowest cost option with basic coverage
Plan G: Most comprehensive, covers nearly all out-of-pocket costs
Plan N: Middle-ground option with small copayments
The best Medigap plan depends on your budget and coverage needs: Plan G costs more monthly but covers more, while Plan A costs less but leaves more out-of-pocket.
Step 5: Verify Your Doctors and Pharmacies Are Covered
Before choosing any plan, confirm your doctors and pharmacies are in-network to prevent surprises later.
Search each plan's provider directory for your doctors' names, checking specialty and location, some plans may not include all doctors in your area.
If your preferred doctor isn't in a plan's network, you have two options:
Choose a different plan that includes your doctor
Accept that you'll pay more to see an out-of-network doctor
Verify your preferred pharmacy is in-network, some plans only cover certain chains. If yours isn't included, request an exception or switch pharmacies.
If unsure, call your doctor's office directly to ask which Medicare plans they accept and confirm the directory is current.
Step 6: Calculate Your Total Out-of-Pocket Costs
When you compare Medicare plans by comparing monthly premiums alone, you don't tell the full story. Two plans with the same premium can differ by thousands of dollars a year once you use care. The reliable method is to build three annual scenarios, low use, typical use, and high use, and run each plan through all three.
What goes into the total
For each plan, add:
Premiums × 12 (Part B premium, plus Part D premium, plus Medigap premium, or the Medicare Advantage premium)
Deductibles you expect to meet (Part A, Part B, Part D, and any plan-level deductible)
Copayments for expected visits, specialist visits, urgent care, and emergency room use
The three-scenario method
Low use, preventive care only, one or two primary care visits, generic drugs.
Original Medicare + Part D + Medigap: mostly premiums plus the Part B deductible; Medigap absorbs most remaining cost-sharing.
Medicare Advantage: premiums plus small copays; the out-of-pocket maximum is unlikely to be reached.
Typical use, several primary care visits, a couple of specialist visits, routine labs, a few generic and one or two brand drugs.
This is where tier placement on the drug formulary starts to matter more than the premium difference.
Compare the plan's copay for each tier against your actual drug list, not against a sample list.
High use, a hospitalization, outpatient procedure, or a specialty drug.
This is where the out-of-pocket maximum does the most work. A plan with a lower maximum caps your worst case; a plan with a higher maximum can cost more even if its premium is lower.
On Original Medicare without Medigap, there is no annual out-of-pocket maximum, so a high-use year is uncapped. That is the single largest cost difference between the two paths.
Watch Out A low premium is not a low total cost. A plan with a $0 premium and a high out-of-pocket maximum can cost more in a high-use year than a plan with a modest premium and a low maximum. Always compare the worst-case number, not just the monthly number.
Worked example structure (use your own numbers)
Build a simple table with one column per plan and one row per cost category:
Cost category
Plan A
Plan B
Plan C
Annual premiums
Deductibles met
Copays (low / typical / high)
Coinsurance (low / typical / high)
Drug costs (low / typical / high)
Annual total, low use
Annual total, typical use
Annual total, high use
Out-of-pocket maximum
Fill it in with your own visit counts and drug list. The plan that wins on low use is often not the plan that wins on high use, and the right choice depends on which scenario you are protecting against.
Enrollment timing and switching rules change the math
A cost comparison is only useful if you can act on it. Three timing rules affect which plans you can actually get and when:
Initial Enrollment Period, a seven-month window around your 65th birthday month. Enrolling late can trigger late-enrollment penalties on Part B and Part D that raise your premiums for as long as you have coverage.
Annual Enrollment Period, October 15 to December 7 each year, with changes generally taking effect January 1. This is when you can switch between Medicare Advantage and Original Medicare, or change Part D plans.
Medicare Advantage Open Enrollment Period, January 1 to March 31, limited to people already in a Medicare Advantage plan; you can switch to another Advantage plan or back to Original Medicare (and add Part D), but generally only once.
Medigap has its own constraint: after your one-time Medigap Open Enrollment Period (a six-month window that starts the month you are 65 or older and enrolled in Part B), insurers in most states can medically underwrite you. That means a health condition can raise your premium or lead to a denial. Some states add guaranteed-issue rights or birthday rules; check your state's rules before assuming you can switch into Medigap later.
Pro Tip Gather your drug list, provider list, and last year's explanation-of-benefits statements before you open Plan Finder. Entering real numbers into the three-scenario table takes about an hour and is the difference between comparing premiums and comparing costs.
SafelyRetire recommends running all three scenarios before you decide. The plan that costs least on paper may not be the plan that costs least in reality once you factor in a high-use year, a drug tier change, or the switching rules that limit your options later.
Frequently Asked Questions
What's the difference between Original Medicare and Medicare Advantage when I compare Medicare plans?
Original Medicare (Parts A and B) covers hospital and medical services through the federal government. Medicare Advantage is an alternative offered by private insurers that includes all Part A and B benefits, often with added dental, vision, or hearing coverage. When you compare Medicare plans, Original Medicare offers broader provider networks nationwide, while Medicare Advantage typically has lower premiums but requires using in-network doctors and hospitals in your area.
How do I check whether my doctors are covered before I compare Medicare Advantage plans?
Use the Medicare Plan Finder tool on Medicare.gov by entering your ZIP code. You can search for specific doctors and hospitals to see which Medicare Advantage plans include them in their provider network. Contact the plan's member services if you need confirmation that a specialist or hospital is in-network.
How do I compare Medicare Part D prescription drug plans to find the lowest medication costs?
Enter your current medications into the Medicare Plan Finder to see estimated annual drug costs for each plan in your area. Compare the plan's deductible, copayments for your specific drugs, and whether your pharmacy is in the plan's network. Check the drug formulary to confirm each medication is covered and at what tier (which affects your out-of-pocket cost).
Can I change my Medicare plan after I enroll, or am I locked in for the year?
You can make changes during the annual Medicare Open Enrollment Period (October 15 to December 7) for coverage starting January 1. If you experience a qualifying life event (such as moving, losing employer coverage, or a significant change in health), you may be eligible for a Special Enrollment Period that allows changes outside the standard window. Guaranteed-issue rights for Medigap also apply in certain situations.
Cooler Weather, More Reasons to Move! Try These Outdoor Activities!
When temperatures begin to drop, spending time outdoors can become more comfortable and enjoyable. Cooler weather offers a great opportunity to step away from screens, get moving and build healthy habits that support your physical and mental well-being. From exploring local trails to enjoying a neighborhood bike ride, simple outdoor activities can help you stay […]